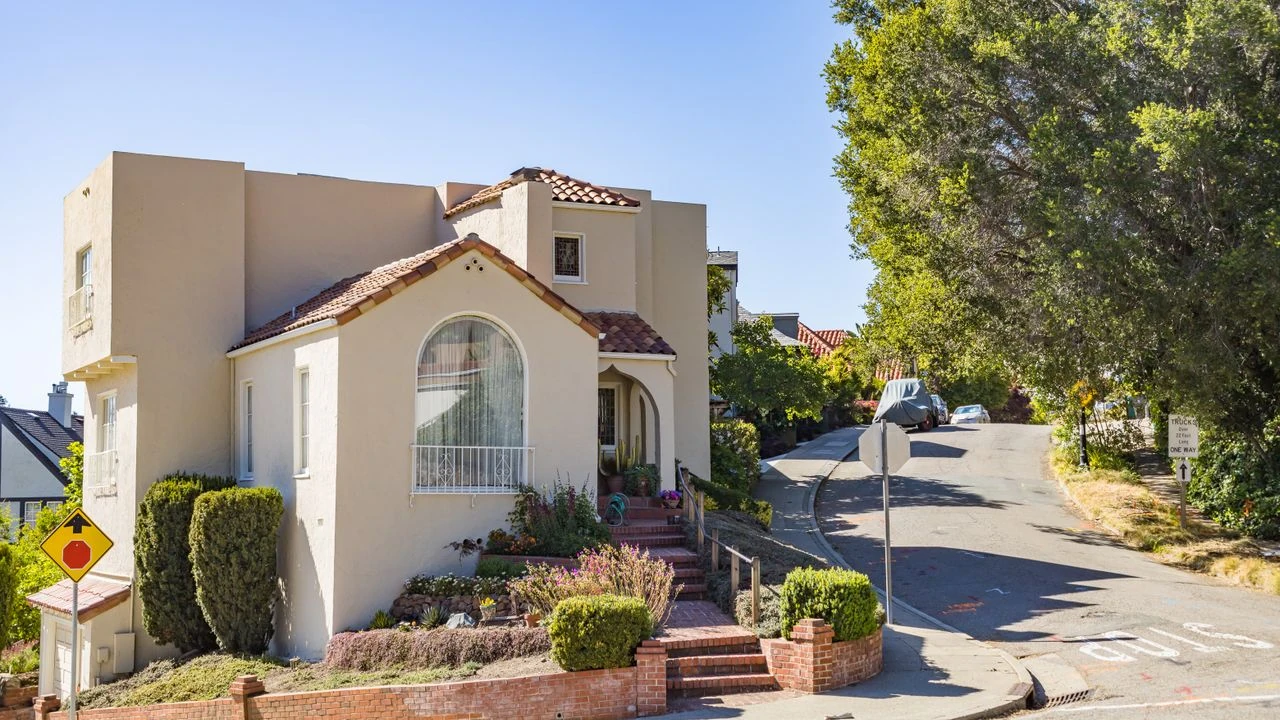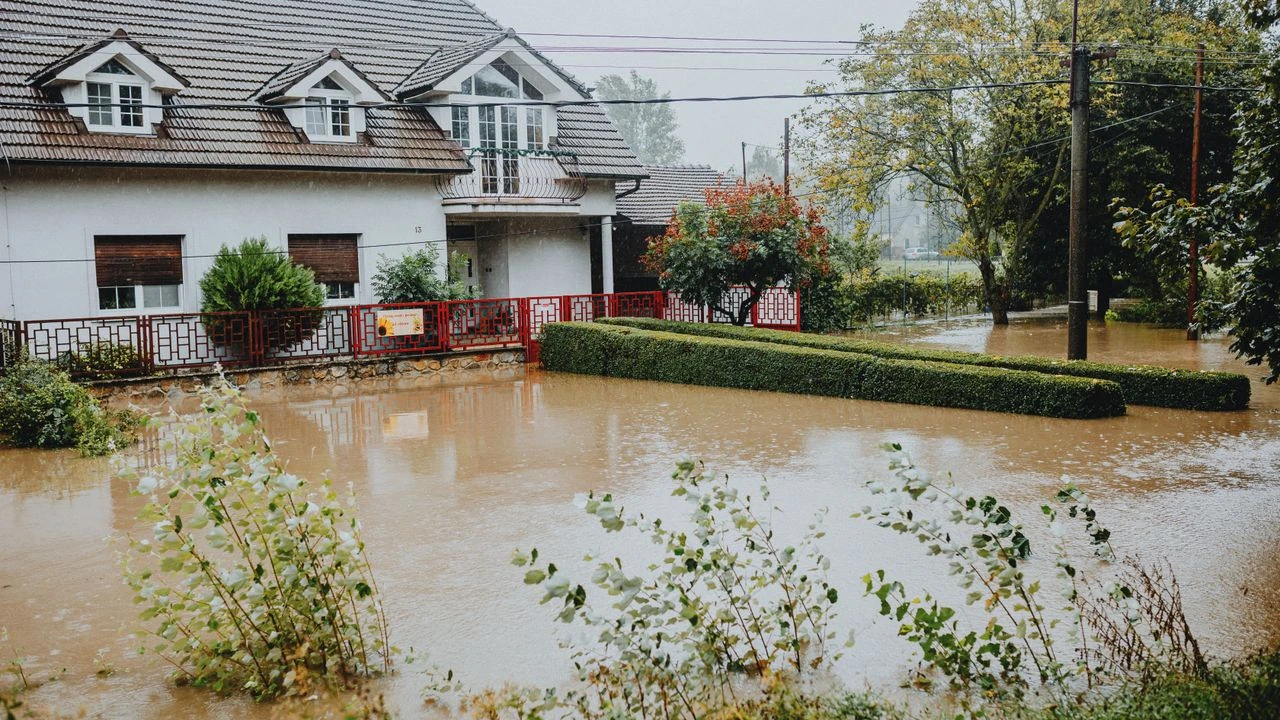
At 8:20 on a Wednesday night my wife Dana opened a government envelope with a butter knife, read one line out loud, and set the letter flat on the dining table like it might bite. Effective January 30, the line said, your property has been remapped from flood zone X into zone AE. We had just finished the dishes. The house sits on the high shoulder of a hill, the kinda lot where neighbors joke about valley views, and a federal map had just declared our kitchen forty feet from a base flood elevation line. Dana read the letter twice. I read the rest of it standing up.
The stakes arrived on the second page in the shape of a number our budget had never met. Because our loan predates all of this and carries an FHA origination from 2019, the servicer is required to force-place flood coverage the moment the map says flood, no opinion offered, and the estimate attached to the letter came to $1,450 a year, escrowed, which meant our monthly payment was about to grow by $121 for the rest of the loan's life. That is a car payment for water we have never seen. It also meant the refinance we had been planning for spring was effectively dead, because nobody refinances into a flood zone at a better mortgage rate and then celebrates. The map had reached inside our finances without a single raindrop falling.
Here is the part I did not know that night, and it is the reason this story ends with a refund instead of a premium. The FEMA map can be argued with, in writing, by the property itself, through a four-letter process called a LOMA that most homeowners have never heard of cuz nothing about it is ever advertised. What it requires is a surveyor, an elevation certificate, and about ninety days of patience, and what it can deliver is your zone back. Our case came down to seven feet. The next three months of my life were spent learning exactly what those seven feet were worth, and who gets to count them.
the envelope that said AE
The letter itself was eight pages, and I have opinions about all of them. The first page announces the remapping in language so calm it reads like a weather report. The next two carry the premium estimate and the legal basis for force-placed coverage. The final five are appeals language, and nobody on the insurance side volunteers that the appeals language applies to you, because their job ends at collecting the premium. I called the servicer the next morning and spent fifty minutes transferred between four departments, each one polite and powerless, before a woman in the flood department said the sentence that changed the quarter. The map is an assumption, she said. Assumptions can be amended. Then she hung up, having no idea she had just handed me a project.
zone X, until January 30
Until this letter, our house had spent its whole life in zone X, the federal shorthand for minimal flood risk, the zone where lenders do not ask and insurers do not bother. The remap came from a countywide restudy, the first since 2009, in which the engineers upstream recalculated the creek's behavior during a hundred-year storm and redrew the AE boundary uphill til it touched our parcel's low corner. Nobody built anything. No water moved. A model changed, and a model is not a flood, it is a forecast wearing a legal hat, and the legal hat is what the bank answers to. I printed the old map and the new map and taped them side by side on the pantry door. The difference between them was one contour line and $1,450 a year.
$1,450 a year, escrowed and silent
The first escrow analysis arrived in February and made the abstract concrete. Payment up $121 a month, effective March 1, no action required on our part, which is exactly the problem, because force-placed coverage requires nothing from you except payment. Our FHA loan made refusal impossible, the servicing agreement treats the flood zone as fact once FEMA says so, and the mortgage rate we had argued down to 5.25 percent in 2019 now lived underneath a fee the rate never voted on. I ran the lifetime math at the table that night and stopped halfway through, cuz if we carried the loan to term, $121 a month for twenty-two more years came to approximately $32,000 of premium against a house that has never seen standing water. Numbers like that reorganize a kitchen table. Ours got quiet.
the surveyor with the orange tripod
A LOMA lives or dies on an elevation certificate, and a certificate lives or dies on a licensed surveyor, so I called three outfits and took the one that called back first, a two-man shop run by a surveyor named Perry who arrived in a truck full of instruments and an orange tripod he set up on my curb like a flag. The whole measurement took two hours and cost $550. Perry shot the lowest grade adjacent to the structure, the lowest finished floor elevation, the lowest horizontal structural member, each number logged against the flood line the map had drawn at 612 feet. He talked while he worked, which I appreciated. Most of the houses on this ridge, he said, are seven to ten feet above the line. The map just hasn't met them yet.
seven feet, measured twice
The certificate came back with the number in the box where it matters, lowest adjacent grade, 619 feet, seven feet above the base flood elevation the map had assigned us. Seven feet is the height of a ceiling. It is the climb the creek would have to make, in the worst storm the model can imagine, before our kitchen floor became part of the conversation. Perry signed and sealed the certificate on February 9, and I made three copies because bureaucracy eats paper. The appeal itself fit in an envelope lighter than the original remap letter. The heavy part was the waiting. FEMA gives itself sixty days by statute and uses most of them.
four letters, none of them FEMA
The form deserves a description, cuz the stakes and the paperwork were laughably mismatched. A LOMA, Letter of Map Amendment, asks for your name, your parcel, your certificate of elevation, and a signature, and its entire premise is that a property physically above the flood line does not belong in the zone and should not carry its insurance. Fee waived, eleven questions, one envelope. I mailed it certified on February 12 and began a calendar countdown my family absorbed to stop asking about. Dana's only comment the whole month was that we had bet $550 on the ground being where Perry said it was. The ground, at least, keeps no secrets. It was the mail that moved slowly.
ninety days by the book
The wait was the worst-funded ordeal I have ever endured, ninety days of an escrow account quietly charging the new premium while the appeal sat in a federal queue. March 1 came and the payment went up, exactly as threatened, $121, and every bill in March and April carried the flood line item for a zone we were formally contesting. I checked the case status page the way other people check sports scores, once a morning, coffee in hand. Week seven, a letter arrived asking for one clarifying page, which everyone online called a bad sign and which meant nothing. Week nine, nothing. Bureaucracy has no concept of theatrical timing. That is its one mercy and its one cruelty.
the refund dated April 20
The approval letter is dated April 20 and it is going in a frame. The map amendment was granted, the property is removed from the special flood hazard area effective with the letter, and the forced coverage, once canceled, refunds on a prorated basis, $1,090 back of the $1,450 that had been assumed. I called the servicer the same afternoon, the cancellation took effect before May, and the escrow analysis that followed dropped our payment by $118 a month, close enough to feel like an apology. Total cost of the fight: $550 to Perry, eleven dollars in certified mail, ninety days of my mornings. Total annual savings: $1,450, every year, for as long as we own the walls. I have made worse trades in my life. Not many.
what the hill always knew
The envelope from January sits in the same drawer as the April approval, two federal letters, eighty days apart, telling the whole story in government font. Our kitchen, the one the map put forty feet from a flood line, still faces the same valley, the creek still runs where it ran, and the ground under the house still sits at 619 feet, indifferent to both letters. What changed is that the ground gotta testify. I think about the $1,450 we would have paid for decades if we had treated the first envelope as weather, unarguable, and I think about the surveyor's orange tripod more than a grown man should. The hill knew what it was the whole time. Now the map knows it too. That is worth a frame.